How to Read a Loan Estimate: Line-by-Line Guide
The Loan Estimate is the most powerful consumer protection in mortgage shopping — a standardized federal form that forces every lender to disclose their terms in identical format. Yet most borrowers glance at the interest rate and ignore the rest, leaving thousands of dollars in negotiable fees on the table. Learning to read this three-page form is worth more than any rate-chasing.
This guide walks through the Loan Estimate page by page: what each section means, which numbers are negotiable, the tolerance rules that protect you, and how to use competing estimates as negotiation weapons. Three pages, thirty minutes, thousands saved.
Key Takeaways
- Federal law requires lenders to deliver it within 3 business days of application.
- Compare Section A (origination charges) across lenders — the purest price signal.
- Page 1 shows rate, payment, and cash to close; page 2 itemizes every cost.
- Tolerance rules: lender fees can't increase at closing; some third-party fees capped at 10%.
- Use rival estimates as leverage — lenders match competitors routinely.
Page 1: The Headlines
- Loan terms: loan amount, interest rate, monthly principal & interest. Check the rate lock status — “NO” means the rate can change.
- Projected payments: payment calculation table showing P&I, mortgage insurance, and estimated escrow — and crucially, whether the payment can change (for ARMs: when, how much, and the maximum).
- Costs at closing: estimated closing costs and estimated cash to close — the bottom-line numbers for comparison.
- APR: the annualized cost including fees — useful as a sanity check, though imperfect for comparison (it assumes you keep the loan full term).
- TIP (total interest percentage): total interest as a percentage of the loan — eye-opening for 30-year loans (often 80-110%).
Page 1 answers: what’s my rate, what’s my payment, what do I bring to closing? Everything else is detail supporting these three numbers.
Page 2: The Itemized Costs (Where the Money Is)
- Section A — Origination Charges: the lender’s own fees (origination, underwriting, processing). Fully negotiable, fully comparable. $0-$2,500+ variance between lenders is normal — this section is why you shop.
- Section B — Services You Cannot Shop For: appraisal, credit report, flood determination — lender-chosen providers. Not negotiable, but comparable.
- Section C — Services You Can Shop For: title search, title insurance, survey, pest inspection. You choose the providers — get competing quotes and save hundreds.
- Section E — Taxes and Government Fees: recording fees, transfer taxes. Set by jurisdiction — not negotiable, but verify accuracy.
- Section F — Prepaids: homeowners insurance, prepaid interest, property taxes. Timing-driven, not profit.
- Section G — Initial Escrow Payment: the cushion funding your escrow account. Formula-driven (capped by law).
- Section H — Other: HOA transfer fees, etc.
- Section J — Total Closing Costs: the sum — your comparison bottom line.
- Lender credits: listed separately — credits offsetting costs in exchange for a higher rate. Factor into total economics.
Pre-Approval vs Pre-Qualification: Know the Difference
Pre-qualification is a casual estimate based on numbers you self-report — income, debts, assets — with no verification. It’s a 10-minute conversation and carries almost no weight with sellers.
Pre-approval is the real thing: the lender verifies your income (pay stubs, W-2s, tax returns), pulls your credit, reviews bank statements, and issues a conditional commitment for a specific loan amount. In competitive markets, offers without a pre-approval letter often go straight to the bottom of the pile.
To get pre-approved, expect to provide: 30 days of pay stubs, two years of W-2s or 1099s, two years of tax returns, two to three months of bank statements (all pages, all accounts), and documentation for any large deposits. Self-employed buyers should plan for extra scrutiny — lenders typically average two years of adjusted net income, and big write-offs that lower your taxes also lower your qualifying income.
A pre-approval letter usually lasts 60-90 days and states a maximum — not a target. Being approved for $550,000 doesn’t mean you should spend it. And protect the approval once you have it: don’t change jobs, don’t make large undocumented deposits, don’t open new credit, and don’t make major purchases on credit until after closing. Lenders verify employment and re-pull credit right before funding; plenty of deals have died the week before closing because of a new car loan.
Underwritten pre-approvals (sometimes called “TBD approvals”) are the gold standard worth asking about. In a standard pre-approval, a loan officer reviews your file; in an underwritten pre-approval, an actual underwriter reviews it — the same person who’ll approve your final loan. It’s a stronger commitment, it surfaces problems while there’s time to fix them, and in competitive markets it can make your offer nearly as strong as cash. Some lenders offer it free; others charge a small fee. If you’re buying in a hot market or have any complexity in your file (self-employment, bonus income, past credit issues), the upgrade is worth it.
Pre-approval shopping doesn’t obligate you to that lender — and you should absolutely compare. Get two or three pre-approvals from different lender types (a bank, a credit union or mortgage broker, and an online lender, for instance) to compare not just rates but responsiveness, fee structures, and program expertise. The pre-approval conversation is also your interview: does the loan officer explain things clearly? Do they answer promptly? You’ll be working intensely with this person for 30-60 days — choose someone competent and communicative, not just the lowest advertised rate.
One more thing the letter doesn’t tell you: it states a maximum, not a recommendation. Being approved for $600,000 when your comfortable budget is $450,000 is normal — lenders don’t know your childcare costs, your savings goals, or your life. Set your own ceiling before you tour a single home, tell your agent the real number (not the approval number), and shop within it. The buyers who stay happiest are the ones whose payment leaves room for the rest of their lives.
Tolerance Rules: Your Legal Protection
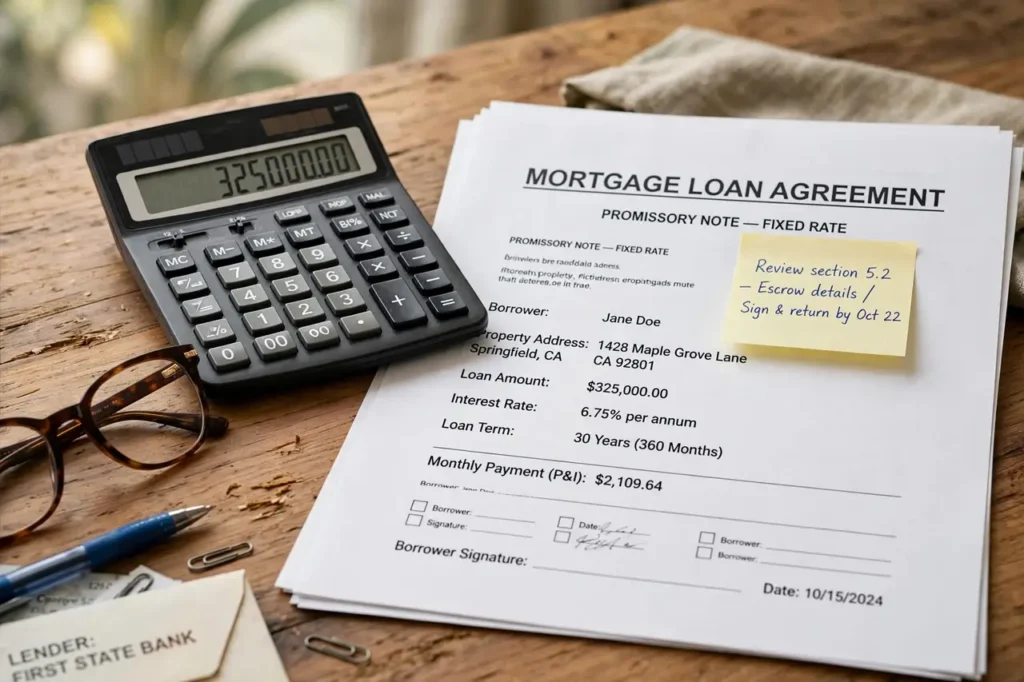
Federal tolerance categories limit how much costs can grow from Loan Estimate to Closing Disclosure:
- Zero tolerance: Section A (lender fees), Section B (lender-chosen services), and transfer taxes — these cannot increase at all. If they do, the lender eats the difference.
- 10% tolerance (bucketed): Section C services (where you didn’t shop) + recording fees — the total can’t exceed the estimate by more than 10%.
- Unlimited: prepaids, escrow, and services you shopped for yourself — these can change with timing and your choices.
Practical use: when the Closing Disclosure arrives 3+ days before closing, compare every line to the Loan Estimate. Section A increases are illegal — dispute them. Section C bucket overages beyond 10% get credited to you. This is your enforcement mechanism; use it.
Also watch for the bait-and-switch pattern: rosy initial estimate, then a “revised” Loan Estimate with higher costs mid-process. Revisions are only legal for specific changed circumstances (rate lock, changed loan terms, etc.) — question every revision.
The Closing Timeline: From Accepted Offer to Keys
Expect 30-45 days from accepted offer to closing day for a financed purchase (cash can close in 1-2 weeks). Here’s the typical sequence:
- Days 1-3: earnest money deposited, disclosures and HOA documents requested, inspector scheduled.
- Days 3-10: inspection period — attend the inspection, negotiate repairs or credits, finalize your decision to proceed.
- Days 10-20: lender orders the appraisal; underwriting reviews your full file. Respond to document requests within 24 hours — delays here are the #1 cause of late closings.
- Days 20-30: appraisal comes back (if low, renegotiate price, increase down payment, or walk away per your contingency), loan receives conditional then final approval.
- 3 days before closing: you receive the Closing Disclosure — federal law requires it at least 3 business days before signing. Compare every line against your Loan Estimate; question anything that moved.
- Closing day: final walkthrough (verify agreed repairs, check that the home is empty and undamaged), then sign the stack — note, mortgage, deed of trust — and fund. Wire fraud is rampant: never wire closing funds based on emailed instructions without verbally confirming with your title company at a known number.
Bring a cashier’s check or confirmed wire for the exact amount on the Closing Disclosure, plus government ID. Budget 2-5% of the purchase price in closing costs: lender fees, title insurance, recording fees, prepaid taxes and insurance. After funding and recording, you get the keys — and the first mortgage payment is typically due the first of the month after a full month passes (close in October, first payment December 1).
The Closing Disclosure is your last line of defense — treat the 3-day review period as sacred. Compare it line by line against your Loan Estimate: lender fees shouldn’t have moved (they’re under zero tolerance), third-party fees have limited wiggle room, and any surprise should be questioned before you sign, not after. Common last-minute issues include misspelled names (which can force re-disclosure and delays), incorrect loan terms, and junk fees that crept in. An hour of careful review can save thousands; nobody else will do it for you.
Wire fraud deserves special paranoia. Criminals target real estate closings with forged wire instructions, and victims have lost entire down payments — often irreversibly. Rules: never wire money based on emailed instructions alone, even if the email looks exactly like your title company. Call a verified phone number (from the company’s website or your original documents, not the email) to confirm every wire. Be suspicious of any last-minute changes to wiring instructions. When in doubt, get a cashier’s check instead. This one precaution protects the largest check you’ll ever write.
Do a final walkthrough within 24 hours of closing — not a week before. Verify the property’s condition hasn’t changed, agreed repairs were completed, and nothing was removed that should have stayed (appliances, fixtures). If something’s wrong, delay closing rather than accepting promises; your leverage evaporates the moment you sign. Bring your contract, your inspection report, and your phone camera. The walkthrough is short, but it’s the last time the seller has any obligation to you — make it count.
Comparing Lenders: The Method
- Same day, same scenario: get estimates from 3-5 lenders on the same morning for identical loan amount, property type, down payment, and lock period. Rates move daily — different-day quotes aren’t comparable.
- Compare in this order: (a) interest rate + points/credits package, (b) Section A total, (c) Section J total closing costs, (d) cash to close, (e) APR as sanity check.
- Normalize points: a 6.5% rate with 1 point isn’t cheaper than 6.75% with 0 points unless you’ll stay past break-even. Convert everything to 5-year total cost for honest comparison.
- Question outliers: a lender dramatically cheaper than the pack is either brilliant or baiting — verify with the tolerance rules and their reviews.
- Negotiate with the forms: “Lender B’s Section A is $800 lower and their rate is 0.125% better — can you match?” Present the actual rival estimate. Lenders respond to paper, not claims.
Insist on the official Loan Estimate form — not “worksheets” or “fee quotes.” Worksheets aren’t bound by tolerance rules; the LE is. A lender who won’t produce an LE is telling you everything.
Loan Estimate: Section Guide
| Section | What's In It | Negotiable? |
|---|---|---|
| A — Origination charges | Lender's own fees | Yes — shop hard |
| B — Can't-shop services | Appraisal, credit report | No, but comparable |
| C — Can-shop services | Title, survey, pest | Yes — choose providers |
| E — Taxes/govt fees | Recording, transfer taxes | No — set by law |
| F — Prepaids | Insurance, interest, taxes | Timing only |
| G — Initial escrow | Escrow cushion | Formula-driven |
| J — Total closing costs | The sum | Your comparison bottom line |
Note: Zero-tolerance: A, B, and transfer taxes cannot increase at closing. C-bucket: 10% max increase.
The True Cost of Homeownership (Beyond the Mortgage)
The mortgage payment is the headline, not the whole story. Experienced homeowners budget with two rules of thumb: the 1% rule (expect annual maintenance around 1% of the home’s value — $4,000/year on a $400,000 home, more for older properties) and the $1-per-square-foot rule (a 2,000 sq ft home ≈ $2,000/year in upkeep). Reality lands somewhere between them.
The predictable bills: property taxes (roughly 0.5-2.5% of value per year depending on state — and they rise), homeowners insurance ($1,500-3,000+/year, more in disaster-prone areas), HOA dues ($200-600+/month where applicable), utilities (typically $200-500/month for a house), and PMI if you put down less than 20%. The unpredictable bills: roof ($8,000-20,000 every 20-30 years), HVAC ($5,000-12,000 every 12-20 years), water heater ($1,000-2,500 every 8-12 years), and appliances in the $500-2,500 range each.
Build a home emergency fund separate from your general savings — aim for $5,000-10,000 to start, growing toward 1-2% of home value. Fund it monthly like a bill. Seasonal maintenance prevents the big surprises: clean gutters twice a year, service HVAC spring and fall, test sump pumps before rainy season, and winterize exterior plumbing before the first freeze. A $150 service call beats a $5,000 emergency every time. When evaluating affordability, add 30-40% on top of PITI for these real costs — if that total still fits your budget with room to save, the home is genuinely affordable.
Opportunity cost is the invisible line item. A $80,000 down payment invested at historical market returns could grow substantially over a decade — that forgone growth is part of buying’s true cost, just as rent increases are part of renting’s. This doesn’t mean buying is wrong; it means the honest comparison includes what your money could have done elsewhere. Buyers who run this math and still choose to buy do so for the right reasons — stability, control, forced savings — rather than the myth that every dollar of a mortgage payment “builds equity” (in the early years, most of it is interest).
Transaction costs punish short stays more than any other factor. Buying costs 2-5% in closing costs; selling costs 6-8% in agent commissions and fees. That ~10% round trip means a $400,000 home needs roughly $40,000 in appreciation just to break even on a quick resale — which is why the five-to-seven-year minimum stay rule exists. If your life might move you in three years (career changes, relationships, growing families), price that risk explicitly: renting for three years is often cheaper than buying and selling, even before counting the stress.
Finally, budget the “first-year pile-on” honestly. New homeowners consistently underestimate year-one spending: immediate repairs the inspection flagged, furniture for larger spaces, tools and equipment (lawn mower, ladder, basic toolkit), and the deferred maintenance the previous owner left behind. Surveys suggest first-year surprise spending averages $10,000-$20,000 beyond the purchase. This isn’t an argument against buying — it’s an argument for reserves. The buyer with a healthy emergency fund experiences these as errands; the buyer without one experiences them as crises.
Red Flags in a Loan Estimate
- Missing sections or vague line items: “miscellaneous fees” without breakdown — demand itemization.
- Rate not locked with no discussion: an unlocked rate on an LE near closing is a gamble you didn’t agree to.
- Huge Section A vs competitors: $2,000+ origination on a standard loan is negotiable padding.
- Discount points you didn’t request: some lenders quote with points to advertise lower rates — ensure you’re comparing 0-point quotes.
- Lender credits hiding a high rate: credits are fine if disclosed and compared — not if they obscure an uncompetitive rate.
- Prepaids that look like fees: understand what’s a true fee versus your own money (insurance, taxes) being collected early.
- Expiration dates: LEs show rate lock and estimate expiration — know both, and don’t let them lapse silently.
The Loan Estimate is a tool of empowerment only if you read it. Thirty minutes with this guide and three competing estimates routinely saves buyers $2,000-$5,000+ — the highest-paid half hour of the home purchase.
Costly Mistakes Buyers Make (and How to Dodge Them)
- Skipping pre-approval and shopping blind. You tour homes, fall in love, then learn your budget is $75,000 lower. Get pre-approved before the first showing.
- Maxing the approval amount. The bank’s ceiling isn’t your comfort zone. Leave margin for maintenance, life changes, and actually enjoying your money.
- Draining savings for the down payment. Keep 3-6 months of expenses in reserve after closing. The water heater doesn’t care that you just bought the house.
- Waiving inspection to win. Occasionally defensible for new construction; reckless for a 1960s home with original everything. At minimum, do an informational inspection.
- Ignoring the total monthly picture. Price the PITI + HOA + PMI + utilities, not the sticker price. A cheaper home with a $500 HOA can cost more monthly than a pricier one without.
- Making big financial moves mid-transaction. New credit cards, car loans, job changes, or large undocumented deposits can delay or kill your loan. Freeze your financial life from application to funding.
- Falling for the house, not the numbers. Staging and fresh paint trigger emotion by design. Run the comps, the inspection math, and the five-year cost projection before you commit — then decide.
The antidote to every one of these is the same: slow down the emotional brain and let the spreadsheet vote. For a purchase this size, paying a few hundred dollars for an independent inspection or an hour of a real-estate attorney’s time is the cheapest insurance you’ll ever buy. When in doubt, consult licensed professionals — a buyer’s agent, a mortgage advisor, and where appropriate, an attorney — before signing anything.
Skipping the final walkthrough — or doing it a week early — is a mistake that costs real money. Properties change between contract and closing: sellers remove fixtures that were supposed to stay, agreed repairs get done poorly or not at all, and new damage appears (a leaking pipe doesn’t care about your closing date). The walkthrough exists for exactly these discoveries, and it only works within 24 hours of closing, with your contract and inspection report in hand. Finding a stripped chandelier or an unrepaired roof flashing the day before closing gives you leverage; finding it the day after gives you a bill.
Underestimating the first-year cash drain is the quiet budget killer. Beyond the down payment and closing costs, new homeowners face moving expenses, immediate repairs the inspection flagged, furniture and essentials for a larger space, and the maintenance surprises that cluster in year one. Buyers who stretch to the absolute maximum for the purchase price — leaving minimal reserves — spend the first year stressed and credit-dependent. Keep three to six months of housing costs liquid after closing; the purchase is the beginning of the spending, not the end of it.
Finally, the emotional mistakes: falling in love with a house before the inspection, waiving contingencies to “win” without understanding the exposure, and letting bidding-war adrenaline override the walk-away number. Every one of these has the same root — deciding with emotion what should be decided with criteria. Write your must-haves, your deal-breakers, and your absolute ceiling before you tour anything, and refer back to them when a granite countertop tries to rewrite your budget. The best deal is the one you can still afford happily in year five.
Frequently Asked Questions
What is a Loan Estimate?
A standardized 3-page federal form lenders must deliver within 3 business days of your mortgage application, showing interest rate, monthly payment, itemized closing costs, and cash to close in identical format across lenders. It’s the only true apples-to-apples comparison tool — insist on it over informal worksheets.
How do I compare Loan Estimates from different lenders?
Get 3-5 estimates on the same day for the identical scenario. Compare in order: rate + points package, Section A (origination fees), Section J (total closing costs), cash to close, then APR as a sanity check. Normalize points to 5-year total cost. Negotiate using rival estimates as leverage.
Can closing costs increase after the Loan Estimate?
Within limits: lender fees (Section A) and lender-chosen services cannot increase at all; shoppable third-party services are capped at 10% total increase; prepaids and escrow can change with timing. Compare the Closing Disclosure line-by-line against the LE 3+ days before closing and dispute violations.
What are discount points on a Loan Estimate?
Prepaid interest (1 point = 1% of loan) buying a lower rate (~0.25% per point). Shown in Section A. Worth it only if you’ll stay past the break-even (points cost ÷ monthly savings, typically 5-7 years). Ensure you’re comparing 0-point quotes across lenders unless you’ve decided to buy points.
What is the difference between interest rate and APR?
Interest rate is the pure borrowing cost; APR folds in fees and points as an annualized percentage — useful for comparing total cost if you keep the loan full term, less useful for short stays. Compare both, but make decisions on rate + Section A + 5-year total cost.
Should I be worried if one lender is much cheaper?
Verify, don’t celebrate. Check it’s a real Loan Estimate (not a worksheet), confirm 0 points and identical scenario, review the lender’s reputation and on-time closing record, and watch for revised estimates mid-process. Genuine bargains exist; bait-and-switch is the classic complaint.

Watch: How To Read Mortgage Loan Estimate and Avoid Getting Ripped Off
Prefer to learn by watching? This video walks through the key concepts covered above — a helpful companion to this guide.
Watch on YouTube: How To Read Mortgage Loan Estimate and Avoid Getting Ripped Off
Keep Reading
- How to Celebrate Kwanzaa for the First Time: Beginner’s Guide
- Trick-or-Treating Guide for First-Time Parents (2026)
- 150+ Cute First Date Anniversary Captions for Him (Sweet & Loving)
- 100+ Cute First Date Anniversary Messages for Him: Sweet Texts & Captions
The Bottom Line
Smart decisions about how to read a loan estimate come down to preparation, not luck. Work through this guide as a checklist, get quotes from multiple professionals before committing, and keep your own budget — not a lender’s maximum — as the final word. For decisions with major financial consequences, consulting a qualified local professional is always worth it. Explore the related guides above to keep building your home-buying knowledge.