Retirement is the largest project most people ever manage — a multi-decade endeavor with moving parts in finance, healthcare, housing, law, and lifestyle, all converging on a single date. Yet most people plan it the way they plan a vacation: a vague sense of the destination, a few bookings, and hope. The difference between a retirement that works and one that strains is rarely luck; it is the unglamorous discipline of working through a checklist while there is still time to act on the answers.
This comprehensive retirement planning checklist covers the essential domains: your numbers (savings, income, expenses), Social Security timing, healthcare and Medicare, housing decisions, estate and legal documents, tax strategy, and the lifestyle design that determines whether retirement feels like freedom or drift. It is educational information, not financial advice — the right answers depend on your assets, health, family, and goals, and a qualified fiduciary financial planner or tax professional can tailor them to your situation. Our money resolutions guide pairs well with this checklist as an annual financial review ritual.
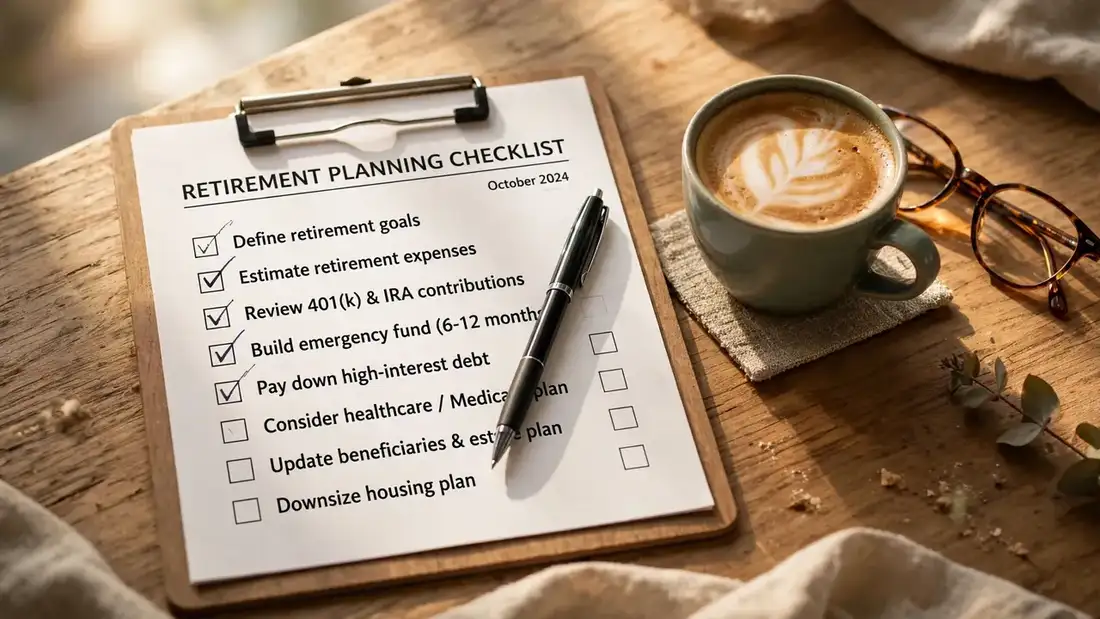
Use this checklist as a working document, not a one-time read. Print it, share it with your spouse or partner, and revisit it yearly — the checklist items do not expire, but your answers change as markets move, health evolves, and the date approaches. The goal is not perfection; it is the absence of preventable surprises. Every item below is actionable, sequenced roughly by when it matters most, and annotated with the mistakes it prevents — work it in order, check items off as you complete them, and note the date of each decision so future you can see the reasoning.
Your Numbers: Savings, Income, and the Gap
Everything starts with arithmetic. Item 1: Know your complete net worth and where it lives. List every account — 401(k)s, IRAs, taxable investments, bank accounts, home equity, business interests, expected pensions — with current balances and tax treatment (tax-deferred, tax-free, taxable). Most people have never seen the full picture on one page; the exercise alone surfaces forgotten accounts and clarifies the tax character of your wealth, which drives everything downstream.
Item 2: Estimate your retirement spending honestly. Track actual spending for at least a year, categorized, because retirement spending is not simply “80% of pre-retirement income” — some costs fall (commuting, payroll taxes, retirement saving itself) while others rise (healthcare, travel, leisure, helping family). Build the budget from your life, not a rule of thumb. Include the lumpy items people forget: home repairs, car replacement, long-term care exposure, and the travel you actually plan to do in the first decade.
Item 3: Project your income sources. Social Security (at various claiming ages), pensions, rental income, part-time work, and portfolio withdrawals. Item 4: Close the gap. Subtract projected income from projected spending; the remainder is what your portfolio must provide. Divide by your portfolio value for a rough withdrawal rate, and compare it to sustainable benchmarks — the classic 4% guideline is a starting point for discussion, not a guarantee, and your planner should stress-test it against market scenarios, longevity, and inflation. If the gap does not close, the levers are: save more, spend less, work longer, or some honest combination — decided now, while the levers still move easily.
Social Security: The Timing Decision
Item 5: Get your benefit estimates. Create an account at ssa.gov and review your earnings record for errors (incorrect earnings history permanently reduces benefits) and your projected benefits at 62, full retirement age, and 70. Item 6: Model claiming strategies. For married couples especially, coordinated claiming — one spouse early, one late; or the lower earner early and the higher earner at 70 to maximize the survivor benefit — can be worth tens of thousands over a lifetime. The survivor benefit angle is underappreciated: the higher earner’s claiming age sets the survivor’s benefit, making delayed claiming by the higher earner a form of longevity insurance for the surviving spouse.
Item 7: Understand the earnings test and taxation. Claiming before full retirement age while still working triggers benefit reductions above the earnings limit; Social Security benefits become taxable at higher income levels (up to 85% taxable). Coordinate claiming with your work plans and Roth conversion strategy — the low-income years between retirement and age 70 are often the ideal window for both delayed claiming and Roth conversions, a powerful combination.
Healthcare and Medicare: The Bridge Years
Item 8: Plan the healthcare bridge to 65. If you retire before Medicare eligibility at 65, you need coverage for the gap: COBRA (expensive, 18 months), ACA marketplace plans (subsidies depend on income — manage your MAGI carefully), a working spouse’s plan, or retiree health benefits. Price this explicitly; the bridge years are among the most expensive healthcare years of early retirement, and underestimating them derails budgets.
Item 9: Master your Medicare decisions. The Initial Enrollment Period, the Medigap-versus-Advantage choice, Part D drug coverage — these are covered in depth in our Medicare guides, but they belong on this checklist because the decisions are time-sensitive and consequential. Item 10: Budget for healthcare realistically. Fidelity’s well-known estimates put lifetime healthcare costs for a 65-year-old couple well into six figures, excluding long-term care. Include premiums, deductibles, dental, vision, and hearing (which Medicare largely excludes) in your retirement budget as a permanent line item.
Item 11: Decide on long-term care. This is the item people most want to skip and least can afford to. Roughly two-thirds of 65-year-olds will need some long-term care; costs run to six figures per year for nursing homes. Your options: self-insure (viable only with substantial assets), traditional long-term care insurance, hybrid life/LTC policies, or Medicaid planning (with its five-year look-back and strict eligibility). There is no universally right answer, but “I haven’t decided” is a decision — for self-insurance by default. Make it deliberately, ideally in your 50s when insurance is cheapest and insurability highest.
Housing: Stay, Downsize, or Relocate
Item 12: Decide the housing question deliberately. Your home is usually your largest asset and your largest expense, and the stay-versus-move decision ripples through finances, lifestyle, and care planning. Staying means budgeting for maintenance, property taxes, and eventual accessibility modifications (stair lifts, bathroom retrofits — plan these before you need them). Downsizing can free equity and reduce costs but involves transaction costs and emotional upheaval. Relocating — to a lower-tax state, closer to family, or into a 55+ or continuing-care community — changes your tax picture, healthcare access, and social network simultaneously.
Item 13: Evaluate aging-in-place modifications early. Walk through your home with fresh eyes: stairs, bathroom layout, doorway widths, lighting, kitchen accessibility. Modifications are far cheaper when planned than when urgent, and universal-design renovations can often be folded into updates you would make anyway. Item 14: Understand the tax implications of housing moves. The home-sale capital gains exclusion ($250,000 single / $500,000 married), state tax differences, and property tax reassessment rules all affect the math. Model the full financial picture of a move, not just the sale price.
Estate and Legal: The Paperwork of Peace of Mind
Item 15: Execute the core documents. Will (or revocable trust), durable financial power of attorney, healthcare power of attorney, living will / advance directive, and HIPAA authorizations. These are covered in our estate-planning guides; the checklist point is binary — done or not done — and “not done” is the most common and most consequential gap in retirement planning. Item 16: Review beneficiary designations. Retirement accounts, life insurance, and annuities pass by beneficiary designation, not by will. Outdated designations — an ex-spouse still named, no contingent beneficiaries — are a quiet catastrophe waiting. Review every account.
Item 17: Organize the “in case of” file. Account inventories, advisor contacts, insurance policies, passwords (via a password manager with emergency access), the location of estate documents, and instructions your executor or agent will need. Tell your people where it is. A perfect estate plan in a drawer nobody knows about fails at its only job. Item 18: Consider incapacity beyond documents. Who knows your wishes? Have you discussed them with your agent and family? The documents are necessary; the conversations make them work.
Tax Strategy: The Decade of Opportunity
Item 19: Map your tax brackets across the retirement timeline. Most retirees face a predictable curve: lower income in the early retirement years (the “tax valley”), then rising income as Social Security, pensions, and RMDs stack up. Item 20: Exploit the valley. Roth conversions, capital gains harvesting, and strategic withdrawal sequencing belong in these low-income years — every dollar converted at 12% instead of 22% (or 24%) is permanent savings, and smaller traditional balances mean smaller future RMDs and lower Medicare IRMAA surcharges.
Item 21: Plan RMDs before they start. Know your RMD age, project your first RMDs, and ensure your 60s strategy accounts for them. Item 22: Coordinate charitable giving. Qualified Charitable Distributions from age 70½, donor-advised funds in high-income years, and charitable bequests of traditional IRA assets (the most tax-efficient asset to leave to charity) should be part of the plan if giving matters to you.
Lifestyle Design: The Forgotten Half of the Checklist
Item 23: Design your time. The research is consistent: retirees who thrive have structure, purpose, and social connection; those who struggle often report the same missing pieces. Before retiring, sketch your ideal week — not the vacation version, the Tuesday version. Work, volunteering, learning, exercise, social time, creative pursuits: the portfolio of activities matters as much as the portfolio of assets. Our New Year resolutions for seniors and retirees offers a yearly framework for keeping the non-financial side intentional.
Item 24: Plan as a couple, honestly. Retirement doubles together-time overnight, and spouses often discover they imagined different retirements. Discuss expectations explicitly: how much togetherness, how much independence, where to live, how to spend, what “enough” looks like. Item 25: Protect your health as an asset. Exercise, preventive care, sleep, and social engagement are not lifestyle luxuries — they are the highest-return investments in your retirement plan, reducing both healthcare costs and the risk of the outcomes no money can fix. The research on longevity is unambiguous that movement, connection, and purpose predict healthy years better than wealth does. The checklist that ignores health is planning the finances of a retirement the body cannot enjoy — so schedule the workouts, the checkups, and the friendships with the same seriousness you schedule the portfolio review.
Retirement Planning Timeline
| When | Priority Checklist Items |
|---|---|
| 10+ years out | Maximize saving; track spending; estimate Social Security; begin estate documents; consider LTC insurance |
| 5 years out | Detailed retirement budget; Social Security claiming strategy; healthcare bridge plan; housing decision; Roth conversion planning |
| 2 years out | Finalize withdrawal strategy; execute Roth conversions; review beneficiaries; organize “in case of” file; test-drive retirement lifestyle |
| 1 year out | Medicare enrollment prep (if 65); confirm income sources; set up cash-flow mechanics; notify employer; plan the first year |
| Retirement year | Execute enrollment/claiming decisions; establish withdrawal cadence; review tax withholding; schedule the annual review habit |
| Every year after | Annual financial review; Medicare plan review (AEP); RMD compliance; beneficiary check; lifestyle check-in |
Sequence of Returns Risk: The Danger Zone
The cruelest math in retirement planning is sequence-of-returns risk: two retirees with identical average returns can have wildly different outcomes depending on when the bad years fall. A market crash in your first years of retirement — while you are withdrawing — permanently impairs the portfolio in a way the same crash a decade later would not, because early withdrawals at depressed prices destroy shares that can never recover. The first five to ten years of retirement are the danger zone, and the plan must account for them explicitly.
Mitigation strategies, none perfect, all useful in combination: maintain a cash buffer (1–2 years of spending) so you are never forced to sell equities in a downturn; keep withdrawal flexibility — the ability to trim discretionary spending 10–20% in bad years dramatically improves portfolio survival; consider a rising equity glide path (starting retirement more conservative, increasing equity exposure over time — the opposite of target-date fund logic, and supported by research on sequence risk); delay Social Security as a form of longevity insurance that reduces portfolio pressure; and explore guaranteed income (pensions, annuities) for essential expenses, which converts market risk into insurer risk. The retirees who sailed through 2008 were not the ones who predicted it — they were the ones whose plans did not require selling stocks at the bottom.
Withdrawal Strategies: Beyond the 4% Rule
The 4% rule — withdraw 4% in year one, adjust for inflation annually — is a useful benchmark and a poor autopilot. Developed from historical simulations, it describes what would have survived past markets, not what will survive future ones, and it ignores taxes, fees, and the reality that nobody spends robotically. Treat it as a conversation starter, then consider the refinements.
Dynamic withdrawal strategies adjust spending based on portfolio performance: the Guyton-Klinger rules, for example, skip inflation increases after down years and trim withdrawals when the withdrawal rate drifts too high. Research consistently shows dynamic strategies support higher lifetime spending than fixed rules with similar failure rates — at the cost of variable income, which requires budget flexibility. The bucket approach segments assets by time horizon (cash for near-term, bonds for mid-term, stocks for long-term) and refills buckets opportunistically; its value is partly psychological — retirees tolerate market drops better when near-term spending is visibly safe — but psychology that prevents panic-selling is real value.
Tax-efficient withdrawal sequencing is the highest-value refinement for most retirees: the conventional order is taxable accounts first, then tax-deferred, then tax-free Roth — but the optimal sequence varies by year, bracket, and goals. In low-income years, accelerate traditional withdrawals or Roth conversions; in high-income years, lean on Roth and taxable accounts with harvested losses. Multi-year tax modeling, not rules of thumb, determines the best sequence — another task where a planner or good software earns its keep. Our money resolutions guide includes an annual withdrawal-strategy review for exactly this reason.
Working With Professionals
Item 26: Assemble your team. Most retirees benefit from some combination of: a fee-only fiduciary financial planner (for the integrated plan), a CPA or tax professional (for the tax strategy), and an estate-planning attorney (for the documents). Interview several, understand how each is compensated, and prefer fiduciaries legally bound to act in your interests. Item 27: Know what advice costs and what it is worth. A good planner’s fee is dwarfed by the value of optimized Social Security timing, tax-efficient withdrawals, and avoided mistakes — but verify value, do not assume it. Ask prospective advisors how they are paid, what a typical engagement covers, and for references.
A word on doing it yourself: capable DIY planners handle much of this checklist well, especially with quality software and education. But consider professional review at the key inflection points — the year before retirement, the Medicare decision, the Social Security decision, and the start of RMDs. An hour of expert review at each inflection point is cheap insurance against the errors that compound for decades. Our financial resolutions for couples guide can help you and your partner align before the professional conversations begin.
Common Gaps: What the Checklist Catches
After years of these conversations, the same gaps recur. The missing estate documents — the most common and most fixable. The unpriced healthcare bridge — early retirees blindsided by $20,000+ annual premiums. The unmade long-term care decision — default self-insurance without the assets to support it. The stale beneficiary designations — ex-spouses and deceased relatives still named. The uncoordinated Social Security claim — the higher earner claiming early without modeling the survivor impact. The ignored tax valley — reaching RMD age with an unconverted traditional balance and wondering where the flexibility went.
None of these gaps reflect intelligence or diligence — they reflect the checklist’s absence. Retirement planning fails not from bad decisions but from undecided ones, the items that sat in the mental “someday” pile until someday became too late. The checklist exists to convert someday into a date.
The First Year: A Month-by-Month Setup Guide
The transition itself deserves a plan, because the first year establishes patterns that persist for decades. Months 1–2: set up cash-flow mechanics — consolidate the paycheck-to-portfolio transition, establish automatic transfers that mimic your old pay schedule (monthly “paychecks” from investments reduce the psychological shock), and confirm health coverage is active. Resist major decisions; the first months are for stabilizing, not optimizing.
Months 3–4: execute the financial setup — confirm Social Security or pension payments, set tax withholding on distributions, establish your withdrawal cadence, and meet your tax professional to calibrate estimated payments. Months 5–6: conduct the lifestyle review — is your time portfolio working? Adjust the mix of structure and freedom deliberately rather than drifting. Months 7–12: run the first annual review early: compare actual spending to the budget, assess the withdrawal rate, confirm beneficiaries and documents are current, and plan next year’s Roth conversions and tax moves. The first year sets the habits — cash-flow discipline, annual reviews, tax awareness — that compound quietly for decades. Get the mechanics right now and the rest of retirement runs on rails you built.
Watch: Retirement Readiness Checklist
This video walks through five steps to assess whether you are truly ready to retire:
Frequently Asked Questions
How much do I need to retire?
It depends on your spending, income sources, longevity, and risk tolerance — there is no universal number. Work the checklist math: projected spending minus Social Security, pensions, and other income equals the portfolio’s job; divide by your savings for a withdrawal rate and stress-test it. Rules of thumb (25x spending, 4% withdrawals) are starting points for planning, not guarantees. A fee-only planner can model your specific situation.
When should I start planning for retirement?
The financial answer is as early as possible — compounding rewards the early. But the checklist answer is: the highest-leverage planning happens in the 5–10 years before retirement, when decisions about Social Security, healthcare bridges, housing, and Roth conversions are still flexible. If retirement is near and you have not started, start this week — late planning beats no planning decisively.
Should I pay off my mortgage before retiring?
It depends on the interest rate, your liquidity, and your temperament. Entering retirement without a mortgage payment lowers your required withdrawals and your stress; but draining liquid savings to do it can leave you cash-poor. Compare the after-tax return of paying down the mortgage against keeping the funds invested, and weigh the psychological value of being debt-free honestly — for many retirees, it is substantial.
How do I know I can afford to retire?
Run the numbers three ways: a base case, a bad-market-early case (sequence-of-returns risk), and a long-life case (to 95). If the plan survives all three with margin, you are in reasonable shape. Then test-drive it: live on your projected retirement budget for six months while still working. The test drive reveals both math problems and lifestyle surprises before they are permanent.
What is the biggest retirement planning mistake?
The undecided items, not the wrong ones: no estate documents, no long-term care decision, no healthcare bridge plan, uncoordinated Social Security claiming. Wrong decisions can be corrected; undecided ones compound silently until options expire. Work the checklist in order and decide each item deliberately.
Do I need a financial advisor to retire well?
Not necessarily — disciplined DIY planners succeed regularly. But professional input pays for itself at the big irreversible decisions: Social Security timing, the Medicare choice, Roth conversion strategy, and long-term care. Consider a one-time plan from a fee-only fiduciary even if you self-manage afterward. For inspiration on what the planning is for, our retirement quotes collection captures the spirit of the endeavor.
The Bottom Line
Retirement planning is a checklist, not a leap of faith. Work your numbers until the gap closes, time Social Security deliberately, bridge healthcare to 65 and master Medicare, decide housing and long-term care on purpose, execute your estate documents, exploit the tax valley, design your days, and review everything annually. No single item is complicated; the power is in completing all of them while the decisions are still yours to make. Start with the item you have been avoiding — it is usually the most important one — and work the list from there. Your future retired self is the beneficiary of every checkbox you tick today, and the best time to start was years ago; the second-best time is this week.
Disclaimer: This article provides general educational information about retirement planning. It is not financial, tax, or legal advice. Individual circumstances vary widely; consult qualified financial, tax, and legal professionals about your specific situation before making decisions.
Taking action on the guidance in this article positions you for better outcomes and greater peace of mind. The time invested in understanding these important topics pays dividends in confidence, security, and the ability to make informed decisions that align with your values and goals. Review this information periodically as circumstances change, consult qualified professionals for personalized advice tailored to your specific situation, and share what you have learned with loved ones who may benefit. Knowledge is most powerful when applied consistently over time, and the steps you take today build the foundation for a more secure and fulfilling tomorrow. Do not postpone the important planning that protects what matters most — begin now with the insights gained here.